Quick answer: For currency futures on Indian exchanges, gross P&L in rupees = (exit price − entry price) × contract multiplier × number of lots for a long (buy) trade. For a short (sell) trade, flip the sign. The multiplier is 1,000 for USD/INR, EUR/INR, GBP/INR and JPY/INR, so every ₹0.0025 tick is worth ₹2.50 per lot. Subtract brokerage, exchange charges, stamp duty and GST to get net P&L.
The core formula:
\text{Net P\&L (INR)} = (P_{\text{exit}} – P_{\text{entry}}) \times M \times L \times d – \text{charges}
Here P is price, M is the contract multiplier, L is the number of lots, and d is +1 for a long trade and −1 for a short. For cross-currency pairs such as EUR/USD, you first get P&L in the quote currency, then convert it to rupees at the RBI reference rate.
This guide walks through each case with worked rupee examples, shows how charges and tax change the result, and ends with a calculator you can build in any spreadsheet.
P&L for INR pairs (USD/INR, EUR/INR, GBP/INR, JPY/INR)
All four INR pairs on NSE have the same tick size and, in practice, the same rupee value per tick.
| Pair | Lot size | Quoted as | Multiplier (M) | Tick | Value per tick per lot |
|---|---|---|---|---|---|
| USD/INR | $1,000 | ₹ per $1 | 1,000 | ₹0.0025 | ₹2.50 |
| EUR/INR | €1,000 | ₹ per €1 | 1,000 | ₹0.0025 | ₹2.50 |
| GBP/INR | £1,000 | ₹ per £1 | 1,000 | ₹0.0025 | ₹2.50 |
| JPY/INR | ¥1,00,000 | ₹ per ¥100 | 1,000 (1,00,000 ÷ 100) | ₹0.0025 | ₹2.50 |
JPY/INR is the one to watch: it is quoted per 100 yen, so the multiplier is 1,000, not 1,00,000.
Worked examples (illustrative prices)
| Trade | Direction | Entry | Exit | Lots | Gross P&L |
|---|---|---|---|---|---|
| USD/INR | Long | 95.5850 | 95.7850 | 10 | (0.20) × 1,000 × 10 = +₹2,000 |
| EUR/INR | Long | 110.0000 | 110.4000 | 2 | (0.40) × 1,000 × 2 = +₹800 |
| GBP/INR | Short | 128.0000 | 127.5000 | 1 | (0.50) × 1,000 × 1 = +₹500 |
| JPY/INR | Long | 64.0000 | 64.3000 | 3 | (0.30) × 1,000 × 3 = +₹900 |
The USD/INR entry price of 95.5850 matches the September 2026 contract on 23 September 2026. The other prices are round illustrative numbers.
Using ticks instead of prices
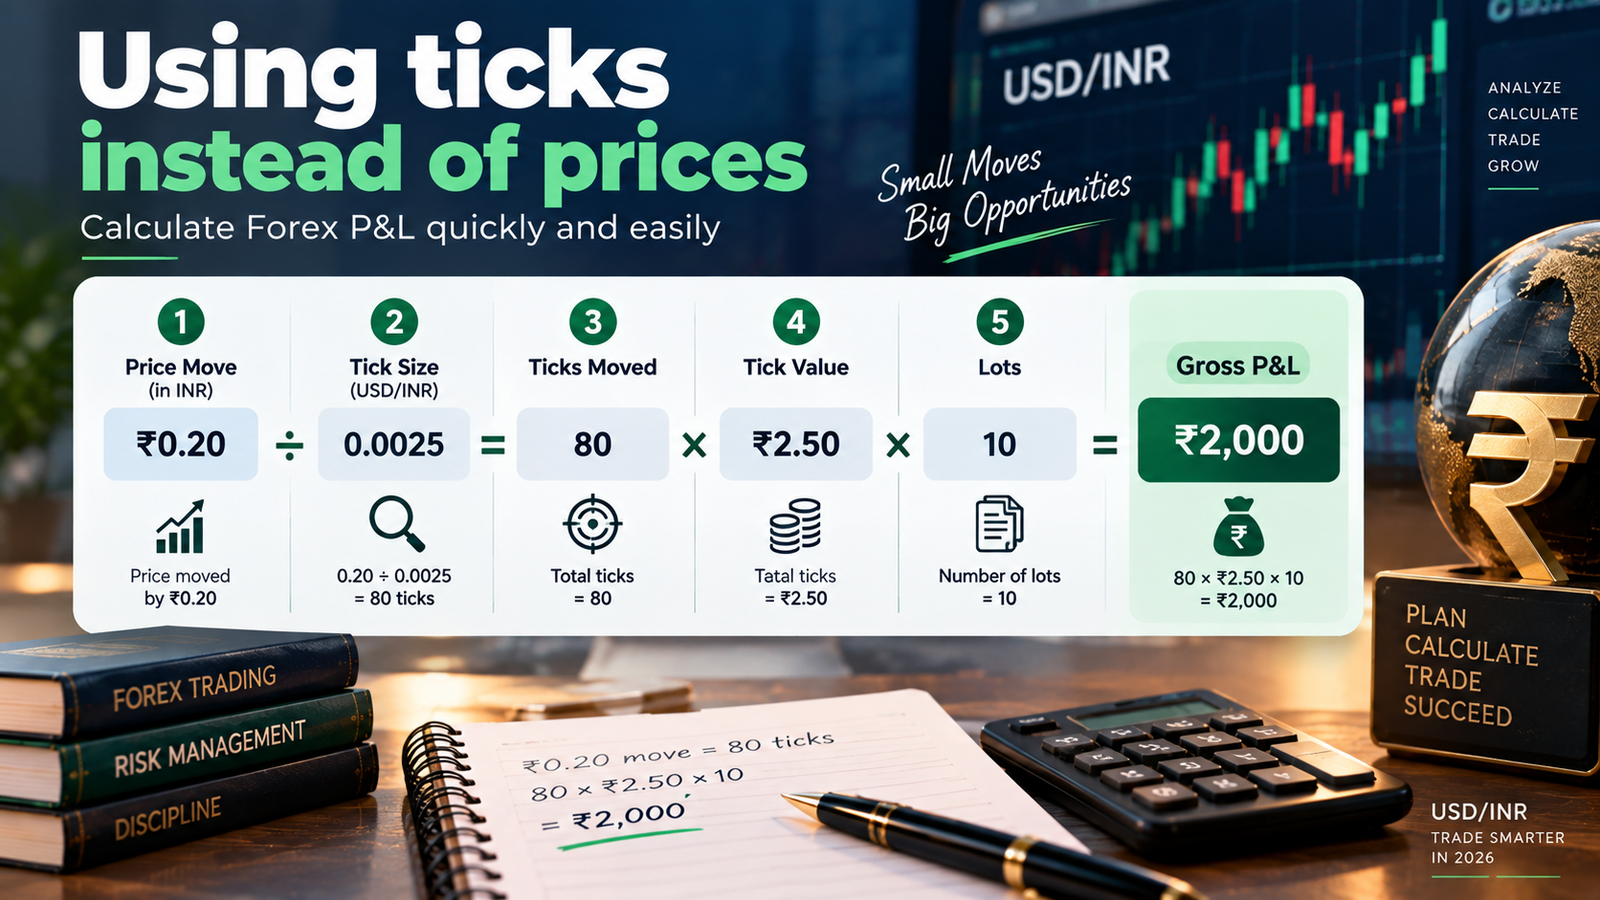
Gross P&L = ticks moved × ₹2.50 × lots.
For the USD/INR trade: a move of ₹0.20 is 0.20 ÷ 0.0025 = 80 ticks. 80 × ₹2.50 × 10 = ₹2,000, the same answer.
Options on INR pairs
For an option buyer: P&L = (exit premium − entry premium) × 1,000 × lots. If held to expiry, the premium at exit is the intrinsic value against the RBI reference rate, or zero.
Example (illustrative): buy 5 lots of a USD/INR call at a premium of ₹0.40, sell at ₹0.55. Gross P&L = 0.15 × 1,000 × 5 = +₹750. The most a buyer can lose is the premium paid: 0.40 × 1,000 × 5 = ₹2,000.
P&L for cross-currency pairs (EUR/USD, GBP/USD, USD/JPY)
NSE also lists three cross-currency futures. They are quoted in dollars or yen but cash-settled in rupees, so there is an extra conversion step.
| Pair | Lot size | Quoted in | Tick | P&L first comes out in | Converted to INR using |
|---|---|---|---|---|---|
| EUR/USD | €1,000 | USD | 0.0001 | US dollars | USD/INR RBI reference rate |
| GBP/USD | £1,000 | USD | 0.0001 | US dollars | USD/INR RBI reference rate |
| USD/JPY | $1,000 | JPY | 0.01 | Japanese yen | JPY/INR RBI reference rate |
Step 1: P&L in quote currency = (exit − entry) × lot size × lots (flip the sign if short).
Step 2: P&L in INR = P&L in quote currency × the RBI reference rate used for that day’s settlement. For USD/JPY, divide the yen amount by 100 first, because JPY/INR is quoted per 100 yen.
Worked examples (illustrative prices)
EUR/USD, long 2 lots from 1.1700 to 1.1750:
- P&L in USD = 0.0050 × 1,000 × 2 = $10
- At a USD/INR reference rate of ₹95.585: $10 × 95.585 = +₹955.85
USD/JPY, long 1 lot from 150.00 to 149.50:
- P&L in JPY = (149.50 − 150.00) × 1,000 = −¥500
- At a JPY/INR reference rate of ₹63.80 per ¥100: (−500 ÷ 100) × 63.80 = −₹319
Because mark-to-market happens daily, a position held over several days is converted at each day’s reference rate, not only the final one. Your broker’s contract notes show the rupee amount for each day.
What about international forex apps?
Many online calculators assume offshore spot forex with standard lots of 100,000 units and pip values in dollars. Trading on overseas online forex platforms is illegal for Indian residents under FEMA, and the RBI keeps an Alert List of unauthorised platforms. This calculator covers only exchange-traded contracts on Indian exchanges.
From gross to net P&L: charges and tax
Charges on currency derivatives (as listed by a large discount broker, September 2026)
| Charge | Currency futures | Currency options |
|---|---|---|
| Brokerage | 0.03% or ₹20 per executed order, whichever is lower | ₹20 per executed order |
| STT / CTT | None | None |
| NSE transaction charge | 0.00035% of turnover | 0.0311% of premium |
| SEBI fee | ₹10 per crore | ₹10 per crore |
| Stamp duty | 0.0001% on buy side | 0.0001% on buy side |
| GST | 18% on brokerage + exchange + SEBI charges | Same |
Unlike equity F&O, currency derivatives carry no securities transaction tax, so charges are low compared with the equity examples in our overtrading guide. Brokerage varies by broker.
Net P&L for the worked examples
| Trade | Gross P&L | Brokerage | Exchange + SEBI + stamp | GST | Total charges | Net P&L |
|---|---|---|---|---|---|---|
| USD/INR long, 10 lots | ₹2,000.00 | ₹40.00 | ₹9.57 | ₹8.75 | ₹58.32 | ₹1,941.68 |
| EUR/INR long, 2 lots | ₹800.00 | ₹40.00 | ₹2.20 | ₹7.56 | ₹49.76 | ₹750.24 |
| GBP/INR short, 1 lot | ₹500.00 | ₹40.00 | ₹1.28 | ₹7.41 | ₹48.68 | ₹451.32 |
| JPY/INR long, 3 lots | ₹900.00 | ₹40.00 | ₹1.92 | ₹7.51 | ₹49.44 | ₹850.56 |
| USD/INR call bought, 5 lots | ₹750.00 | ₹40.00 | ₹1.48 | ₹7.47 | ₹48.95 | ₹701.05 |
The ₹40 brokerage (₹20 on each side) is the biggest charge in every row. On a small trade it matters a lot: one USD/INR lot needs a move of about 16 ticks (4 paise) just to cover about ₹40 of brokerage.
Break-even move
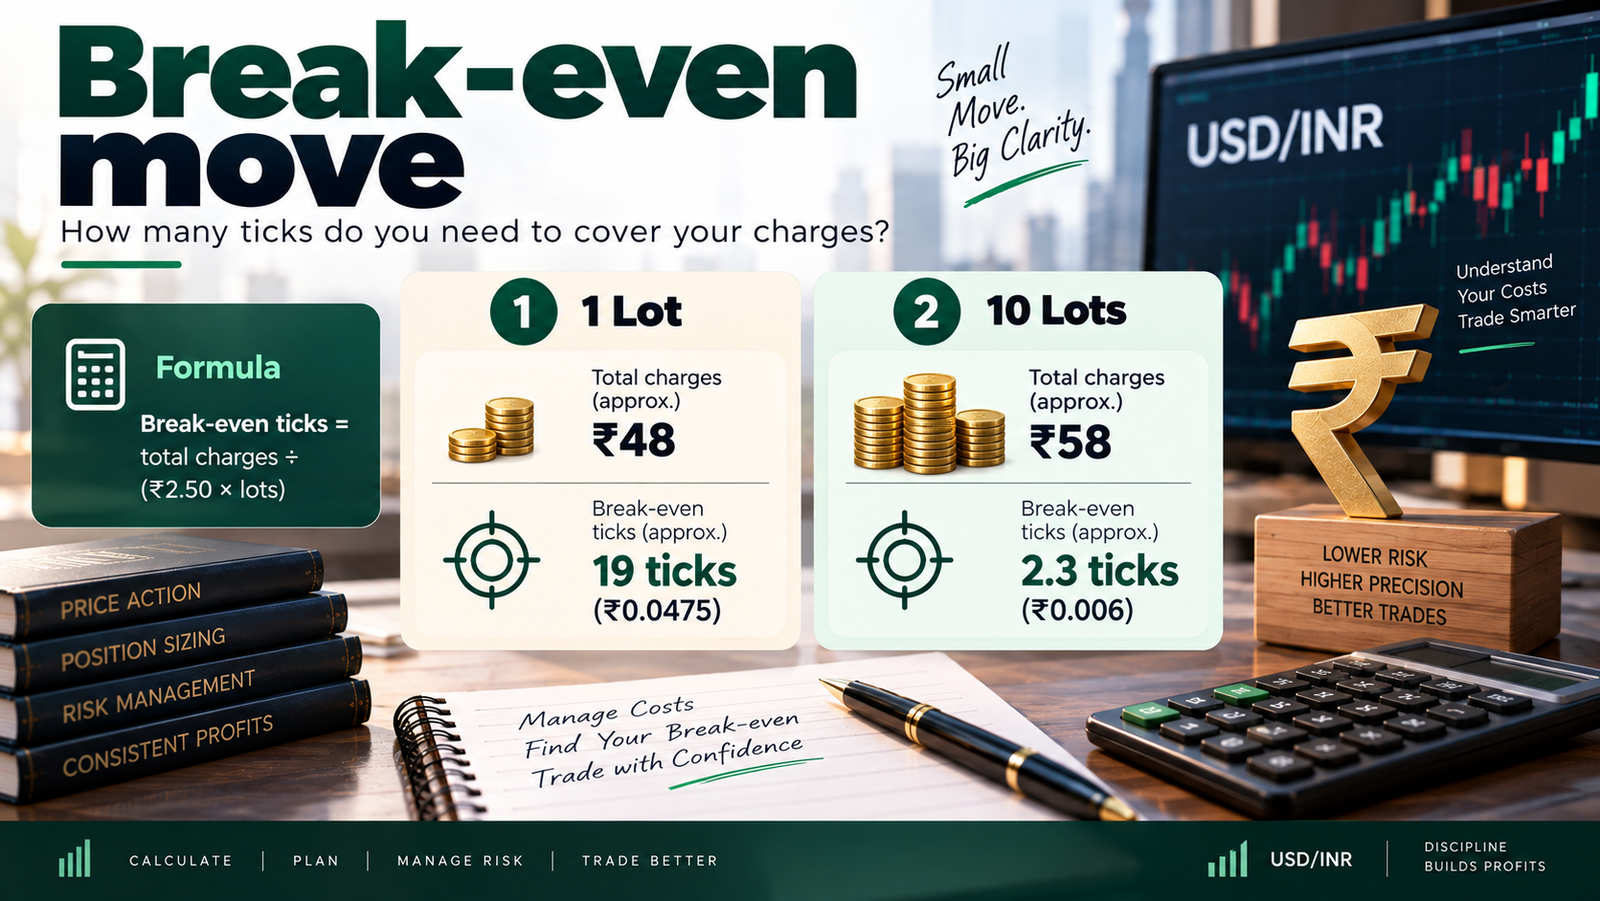
Break-even ticks = total charges ÷ (₹2.50 × lots)
- 1 lot, about ₹48 charges: about 19 ticks (₹0.0475)
- 10 lots, about ₹58 charges: about 2.3 ticks (₹0.006)
Because brokerage is flat per order, bigger trades have a much smaller break-even move per lot.
How currency derivative profits are taxed
- Income from exchange-traded currency derivatives on a recognised Indian exchange is generally treated as non-speculative business income, not capital gains.
- It is added to your other income and taxed at your slab rate. It is usually reported in ITR-3.
- Charges and other genuine trading expenses can be deducted from gross profit.
- A net loss can generally be set off against other non-salary income and carried forward to set off against future business income.
- The Income-tax Act, 2025 replaced the 1961 Act from 1 April 2026, so section numbers you see in older guides may have changed.
Tax rules depend on your full situation, including turnover, audit thresholds and presumptive schemes. Confirm your treatment with a chartered accountant before filing.
The calculator: inputs, formulas and a spreadsheet version
Use this spec to build the on-page calculator widget or a simple spreadsheet.
Inputs
| Input | Example | Notes |
|---|---|---|
| Pair | USD/INR | Sets the multiplier and conversion rule |
| Direction | Long | Long = +1, Short = −1 |
| Entry price | 95.5850 | For JPY/INR, price per ¥100 |
| Exit price | 95.7850 | |
| Lots | 10 | |
| Conversion rate (cross pairs only) | 95.585 | USD/INR rate for EUR/USD and GBP/USD; JPY/INR per ¥100 for USD/JPY |
| Brokerage per order | ₹20 | Change to match your broker |
Formulas
| Output | Formula |
|---|---|
| Contract multiplier (M) | 1,000 for all INR pairs, EUR/USD, GBP/USD and USD/JPY |
| Price move | Exit − Entry |
| Ticks moved | Price move ÷ tick (0.0025 for INR pairs; 0.0001 for EUR/USD and GBP/USD; 0.01 for USD/JPY) |
| Gross P&L, INR pairs | Price move × M × lots × direction |
| Gross P&L, EUR/USD or GBP/USD | Price move × M × lots × direction × USD/INR rate |
| Gross P&L, USD/JPY | Price move × M × lots × direction ÷ 100 × JPY/INR rate |
| Turnover | (Entry + Exit) × M × lots (convert to INR for cross pairs) |
| Charges | Brokerage + 0.00035% of turnover + ₹10 per crore + 0.0001% of buy value + 18% GST on (brokerage + exchange + SEBI) |
| Net P&L | Gross P&L − charges |
| Return on margin | Net P&L ÷ margin used |
Spreadsheet version (INR pairs, futures)
Put inputs in these cells: B1 entry, B2 exit, B3 lots, B4 direction (1 or −1), B5 brokerage per order.
| Cell | Label | Formula |
|---|---|---|
| B7 | Gross P&L | =(B2-B1)*1000*B3*B4 |
| B8 | Buy value | =IF(B4=1,B1,B2)*1000*B3 |
| B9 | Sell value | =IF(B4=1,B2,B1)*1000*B3 |
| B10 | Brokerage | =MIN(B5,0.0003*B8)+MIN(B5,0.0003*B9) |
| B11 | Exchange charge | =0.0000035*(B8+B9) |
| B12 | SEBI fee | =(B8+B9)*10/10000000 |
| B13 | Stamp duty | =0.000001*B8 |
| B14 | GST | =0.18*(B10+B11+B12) |
| B15 | Total charges | =SUM(B10:B14) |
| B16 | Net P&L | =B7-B15 |
| B17 | Break-even ticks | =B15/(2.5*B3) |
Check: with 95.585, 95.785, 10 lots, long and ₹20 brokerage, the sheet gives a gross P&L of ₹2,000, charges of ₹58.32 and a net P&L of ₹1,941.68, matching the table above.
Return on margin
On 23 September 2026, margin was about ₹2,281 per USD/INR lot. For the 10-lot trade, margin used is about ₹22,810.
Return on margin = ₹1,941.68 ÷ ₹22,810 ≈ 8.5% on a 20-paise move. The same move against you would be a similar percentage loss, which is why leverage cuts both ways.
Expert analysis
Fact: all four INR pairs on NSE have a ₹0.0025 tick and a 1,000 multiplier, so one tick is worth ₹2.50 per lot. Cross pairs settle in rupees after conversion at the RBI reference rate.
Fact: currency derivatives carry no securities transaction tax. Brokerage is usually the largest charge.
Analysis: because brokerage is a flat ₹20 per order, charges eat a far bigger share of small trades. A one-lot trade needs about 19 ticks just to break even; a ten-lot trade needs about two. Beginners who trade single lots often find that charges wipe out most small wins.
Analysis: for cross pairs, your rupee P&L carries two exposures: the pair itself and the USD/INR or JPY/INR conversion rate. A trade can be profitable in dollars but show a smaller rupee gain if the rupee strengthens over the holding period.
Analysis: for hedgers, the P&L on the futures leg is only half the picture. The goal is to offset a loss or gain on the actual import or export, so judge the hedge on combined results, not the futures P&L alone.
Opinion: always calculate net P&L and return on margin before you celebrate a trade. Gross P&L flatters small, frequent trades.
Common mistakes
- Using 1,00,000 as the multiplier for JPY/INR instead of 1,000.
- Applying offshore-forex pip values ($10 per pip per standard lot) to Indian exchange contracts.
- Forgetting to convert EUR/USD or USD/JPY P&L into rupees at the RBI reference rate.
- Ignoring brokerage, which can be most of the charges on one-lot trades.
- Treating currency derivative profits as capital gains when filing tax.
- Judging a hedge by the futures P&L alone.
Myths vs facts
| Myth | Fact |
|---|---|
| A pip is always worth $10 | On NSE INR pairs, one tick is worth ₹2.50 per lot |
| Currency futures pay STT like equity F&O | There is no STT or CTT on currency derivatives |
| JPY/INR lots are tiny because the yen is cheap | Each lot is ¥1,00,000, with the same ₹2.50 tick value |
| Cross-pair profits are paid in dollars | They are settled in rupees at the RBI reference rate |
| Currency trading profit is capital gains | It is generally non-speculative business income, taxed at slab rates |
Key takeaways
- Gross P&L = (exit − entry) × 1,000 × lots, with the sign flipped for a short.
- One tick is ₹0.0025 = ₹2.50 per lot for USD/INR, EUR/INR, GBP/INR and JPY/INR.
- JPY/INR is quoted per ¥100; its multiplier is still 1,000.
- EUR/USD and GBP/USD P&L is converted at the USD/INR reference rate; USD/JPY at the JPY/INR rate per ¥100.
- Net P&L = gross P&L minus brokerage, exchange charges, SEBI fee, stamp duty and GST.
- Single-lot trades need about 19 ticks to break even because of flat brokerage.
- Profits are generally non-speculative business income; confirm with a chartered accountant.
FAQs
1. How do I calculate forex profit and loss in INR?
For INR pairs on Indian exchanges, multiply the price difference by 1,000 and by the number of lots. Flip the sign for a short trade, then subtract charges.
2. How much is one tick worth in USD/INR futures?
One tick is ₹0.0025, worth ₹2.50 per lot of $1,000.
3. Is the tick value the same for EUR/INR, GBP/INR and JPY/INR?
Yes. All four INR pairs have a ₹0.0025 tick and a 1,000 multiplier, so each tick is worth ₹2.50 per lot.
4. Why is the JPY/INR multiplier 1,000 and not 1,00,000?
JPY/INR is quoted in rupees per ¥100. One lot of ¥1,00,000 is 1,000 units of ¥100, so the multiplier is 1,000.
5. How do I calculate P&L on EUR/USD futures in rupees?
Work out the P&L in US dollars (price move × €1,000 × lots), then multiply by the USD/INR RBI reference rate used for settlement.
6. How is USD/JPY P&L converted to INR?
Work out the P&L in yen, divide by 100, then multiply by the JPY/INR RBI reference rate, which is quoted per ¥100.
7. What is the formula for forex P&L?
P&L = (exit price − entry price) × contract multiplier × lots × direction, where direction is +1 for long and −1 for short.
8. What charges apply to currency futures in India?
Brokerage, an NSE transaction charge of 0.00035%, a SEBI fee of ₹10 per crore, stamp duty of 0.0001% on the buy side, and 18% GST. There is no STT.
9. How many ticks do I need to break even on one lot?
With about ₹48 of charges at ₹20 brokerage per order, roughly 19 ticks, or about 4.75 paise.
10. How are currency futures profits taxed in India?
They are generally treated as non-speculative business income and taxed at your slab rate, usually reported in ITR-3. Confirm with a chartered accountant.
11. Can I set off currency trading losses?
Non-speculative business losses can generally be set off against other non-salary income and carried forward against future business income. Rules have conditions, so check with a tax professional.
12. How do I calculate P&L for USD/INR options?
For a buyer: (exit premium − entry premium) × 1,000 × lots. The maximum loss is the premium paid.
13. What is return on margin?
It is net P&L divided by the margin used. A ₹1,942 net profit on ₹22,810 margin is about 8.5%.
14. Can I use an international forex pip calculator for NSE contracts?
No. International calculators assume offshore lot sizes and dollar pip values. NSE contracts use ₹0.0025 ticks worth ₹2.50 per lot.
15. Is it legal to trade forex in India?
Indian residents may trade permitted currency pairs on recognised Indian exchanges, subject to RBI rules. Trading on overseas online forex platforms is illegal under FEMA.
16. Which rate is used to settle currency futures at expiry?
The RBI reference rate on the last trading day. Settlement is in cash, in rupees.