Quick answer
Forex profit is business income, not capital gains. Because a currency-derivative contract isn’t a capital asset, the gain is non-speculative business income – so the forex trading income tax slab in India applies (your normal slab rate, up to 30%), it’s filed on ITR-3, and expenses and losses get business treatment.
Introduction
Many traders assume forex profit is taxed like their stock investments – at the lower capital-gains rates. It isn’t, and that assumption leads to wrong forms, wrong rates and sometimes notices. The question of capital gains versus business income is the single most important classification decision for a trader, because it determines the forex trading income tax slab in India that applies to you and how your losses are treated.
This guide settles the question clearly: what each category means, why forex sits in the business-income bucket, how the two compare, and which is actually more favourable in practice. For the full computation and filing steps, see our detailed tax and ITR guides. This is educational information, not tax advice – consult a chartered accountant for your own case.
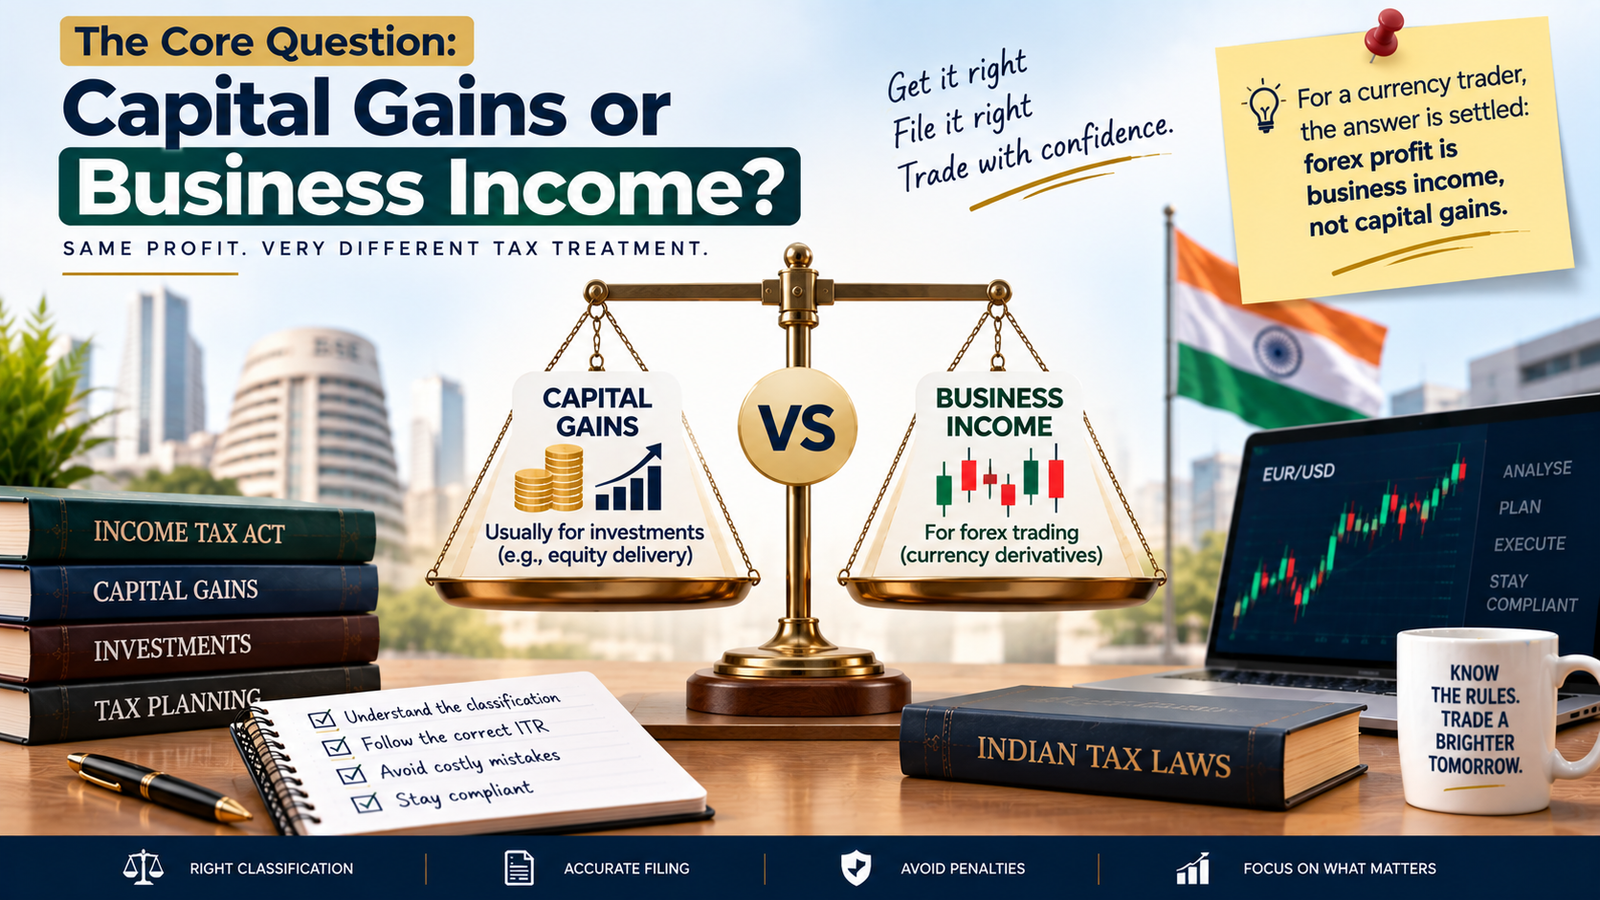
The Core Question: Capital Gains or Business Income?
Indian tax law taxes ‘capital gains’ and ‘business income’ very differently, and the same rupee of profit can attract wildly different tax depending on which bucket it falls into. For a currency trader, the answer is settled: forex profit is business income, not capital gains. Getting this right at the outset avoids the most expensive mistake a trader can make on their return.
What Is Capital Gains Tax?
Capital gains arise when you sell a capital asset – something you hold as an investment, like shares, equity ETFs, mutual funds, gold or property – at a profit. They come in two flavours:
- Short-term capital gains (STCG) – on assets held for a short period; for listed equity, taxed at a fixed rate (around 20%).
- Long-term capital gains (LTCG) – on assets held longer; for listed equity, taxed at a lower fixed rate (around 12.5%) above an exemption.
The appeal of capital gains is those fixed, often lower rates. But they apply only to genuine capital assets held for investment – which is exactly why they don’t apply to forex trading.
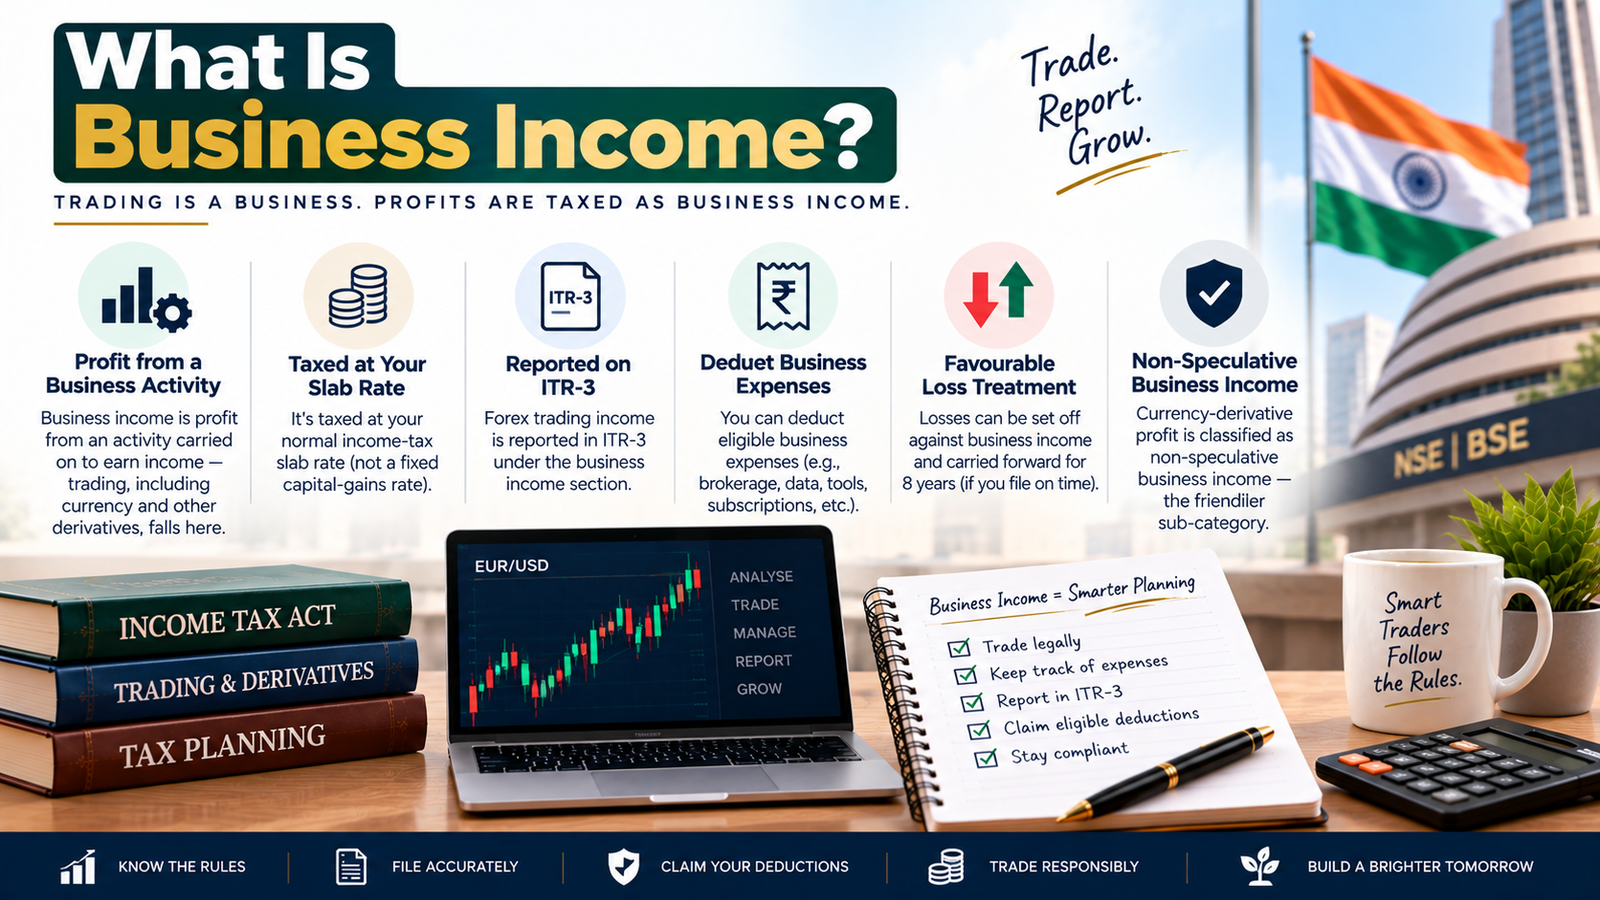
What Is Business Income?
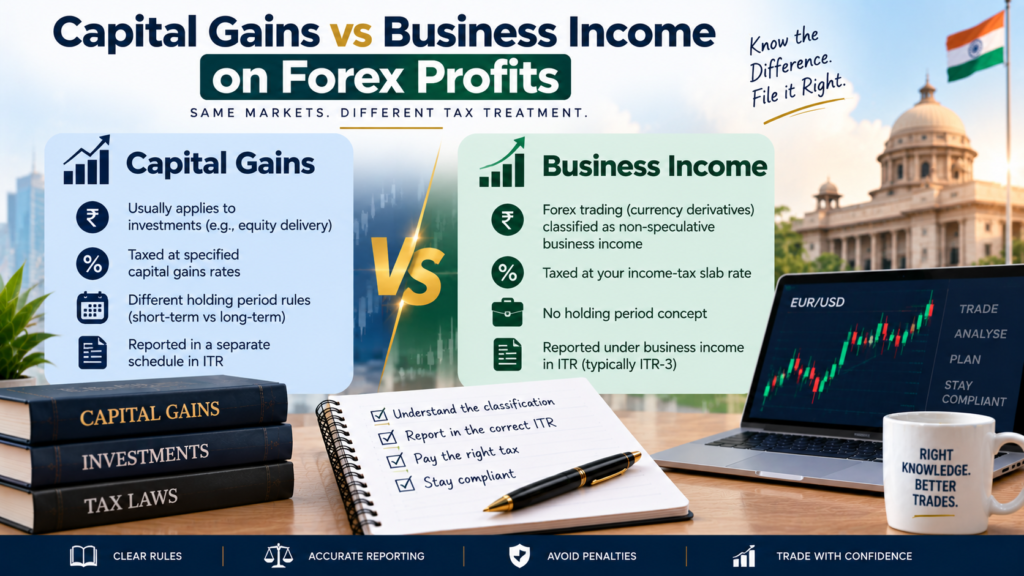
Business income is profit from an activity carried on to earn income – and trading, including currency and other derivatives, falls here. It’s taxed at your normal slab rate rather than a fixed capital-gains rate, reported on ITR-3, and – importantly – it lets you deduct business expenses and gives favourable loss treatment. Within business income, currency-derivative profit is non-speculative business income, the friendlier sub-category.
Why Forex Profits Are Business Income
The legal reason is precise: a derivatives contract is not a ‘capital asset’ under the income-tax law. Capital-gains tax applies to capital assets; since a currency future or option isn’t one, its profit can’t be a capital gain. Instead, it falls under business income – specifically non-speculative business income under Section 43(5)(d), because it’s an exchange-traded derivative. This is true regardless of how often you trade: even a single currency-derivative trade produces business income, not a capital gain. The classification is about the nature of the instrument, not your trading style.
Capital Gains vs Business Income: Side by Side
Seeing the two treatments together makes the difference concrete (rates are indicative; confirm current figures):
| Aspect | Capital gains (investing) | Business income (trading) |
|---|---|---|
| Applies to | Capital assets held as investments (shares, ETFs, property) | Trading, including currency and other derivatives |
| Tax rate | Fixed – roughly STCG ~20%, LTCG ~12.5% for equity | Your slab rate (up to 30%) – the tax slab applies |
| ITR form | ITR-2 | ITR-3 |
| Expenses | Limited deductions | Business expenses fully deductible |
| Loss treatment | Restricted set-off and carry-forward | Broad set-off (not vs salary) and 8-year carry-forward |
| Does forex sit here? | No | Yes – forex derivatives are business income |
Investor vs Trader: The Dividing Line
The confusion usually comes from mixing two different activities:
Investing (capital gains)
If you buy foreign shares or ETFs and hold them as investments, the profit on selling is capital gains – taxed at the fixed STCG/LTCG rates and reported on ITR-2. That’s the investor’s world.
Trading currency derivatives (business income)
If you trade currency futures and options, the profit is business income – taxed at your slab and reported on ITR-3. That’s the trader’s world, and it’s where forex lives. The same person can be both: an investor for their foreign-stock portfolio and a trader for their currency derivatives, with each stream taxed under its own rules.
The Forex Trading Income Tax Slab
Because forex profit is business income, the forex trading income tax slab in India is simply your regular income-tax slab – the profit is added to your total income and taxed accordingly. The current structures (confirm exact bands and any rebate):
| Regime | Rate structure |
|---|---|
| New regime (default) | 0 / 5 / 10 / 15 / 20 / 25 / 30% |
| Old regime | 0 / 5 / 20 / 30% |
So a trader in a lower-income year may pay little on their forex profit, while a high earner could see it taxed at 30%. There’s no separate ‘forex rate’ – it’s whatever slab your total income reaches.
Which Is ‘Better’ – Capital Gains or Business Income?
It’s tempting to envy the capital-gains rates, but the comparison isn’t one-sided. Capital gains can be taxed at a lower fixed rate, which suits a high earner with large gains. But business income offers two things capital gains doesn’t: you can deduct your trading expenses (brokerage, internet, advisory fees, depreciation) to lower the taxable profit, and you get the generous eight-year loss carry-forward with broad set-off. For an active trader who incurs real costs and the occasional losing year, the business-income treatment is often more valuable overall – even if the headline rate can be higher. In any case, for forex it isn’t a choice: the instrument decides, and it’s business income.
What This Means for Your Filing
- File on ITR-3 – the business-income return, not ITR-2.
- Apply your slab rate – the profit is added to total income; no capital-gains rate applies.
- Deduct expenses – reduce taxable profit with legitimate trading costs.
- Use the loss rules – set off and carry forward losses for eight years by filing on time.
- Keep streams separate – investments (capital gains) and trading (business income) are reported under their own heads.
Common Mistakes
- Treating forex profit as capital gains and using ITR-2 with the wrong rate.
- Trying to claim LTCG’s lower rate on derivative profits – it doesn’t apply.
- Not deducting trading expenses that business income allows.
- Mixing investment (capital gains) and trading (business income) under one head.
- Assuming the classification changes with how often you trade.
Myths vs Facts
| Myth | Fact |
|---|---|
| Forex profit is capital gains. | It’s business income; a derivative isn’t a capital asset. |
| Holding longer makes it LTCG. | Currency derivatives can’t be LTCG; they’re business income regardless. |
| Capital gains is always better. | Business income allows expense deductions and 8-year loss carry-forward. |
| The slab doesn’t apply to trading. | It does – forex business income is taxed at your normal slab. |
Tax disclaimer
This article is for educational purposes only and is not tax, legal or investment advice. Slab rates, capital-gains rates, bands and rules change with every Budget, and the new Income-tax Act, 2025 applies from FY 2026-27. Individual situations vary. Details here were checked against 2026 sources but may since have changed. Always verify current rules with the Income Tax Department and consult a qualified chartered accountant.
Learn more about TCS on Foreign Remittance for Trading, Explained
Expert Analysis
The capital-gains-versus-business-income question trips up traders because it feels like a choice when it isn’t. For genuine investments, the investor-versus-trader distinction genuinely matters and can be argued; for exchange-traded currency derivatives, the law removes the argument entirely by declaring that a derivative isn’t a capital asset. Once that’s understood, the wish for capital-gains rates on forex profit reveals itself as a category error – you cannot apply the tax treatment of an asset you never held to a contract that was never a capital asset. The forex trading income tax slab in India applies because the profit is business income, full stop, and the sooner a trader accepts that, the cleaner their filing becomes.
The more useful insight is that business income, for an active trader, is often the better deal in disguise. The envy of the fixed 12.5% long-term rate ignores what business income uniquely permits: every legitimate cost of trading – brokerage, data, advisory, depreciation, a share of home-office expenses – comes off the top before tax, and a bad year’s losses can be set off against most other income and carried forward for eight years. A capital-gains investor gets neither the expense deductions nor that loss flexibility. So a trader who keeps clean expense records and files even in loss years frequently ends up taxed more favourably in substance than the headline slab rate suggests, while an investor with a large one-off gain benefits from the fixed rate. Neither treatment is universally superior; they simply suit different activities – and for forex, the activity is trading, so business income it is. The right response is not to fight the classification but to use its advantages.
Key Takeaways
- Forex profit is business income, not capital gains – a derivative isn’t a capital asset.
- The forex trading income tax slab in India is your normal slab rate (up to 30%), on ITR-3.
- Capital gains (fixed STCG/LTCG rates) apply to investments like shares – the investor’s world.
- Business income allows expense deductions and an 8-year loss carry-forward – often more valuable.
- Keep investment and trading streams separate, each taxed under its own head.
Frequently Asked Questions (FAQ)
Q: Is forex profit capital gains or business income?
A: Business income. A currency-derivative contract isn’t a capital asset, so its profit is non-speculative business income, not capital gains.
Q: What tax slab applies to forex trading?
A: Your normal income-tax slab – the forex profit is added to your total income and taxed at whatever slab that reaches, up to 30%.
Q: Why isn’t forex taxed as capital gains?
A: Because capital-gains tax applies only to capital assets, and a derivatives contract isn’t one under the income-tax law.
Q: Can I get the lower LTCG rate on forex?
A: No. Long-term capital gains rates apply to capital assets held for investment; currency derivatives are business income and can’t be LTCG.
Q: Which ITR form do I use for forex profit?
A: ITR-3, the return for business or professional income – not ITR-2, which is for capital gains and investments.
Q: What’s the difference between an investor and a trader for tax?
A: An investor holds capital assets and pays capital gains; a trader (including currency derivatives) earns business income taxed at slab rates.
Q: Is business income always taxed higher than capital gains?
A: Not necessarily. The slab can be higher, but business income allows expense deductions and 8-year loss carry-forward, often offsetting that.
Q: Do trading expenses reduce my tax?
A: Yes. As business income, brokerage, internet, advisory fees and depreciation are deductible, lowering your taxable profit.
Q: How are forex losses treated?
A: Non-speculative losses set off against most income (not salary) and carry forward eight years, if you file on time.
Q: Does how often I trade change the classification?
A: No. Currency-derivative profit is business income regardless of frequency – even a single trade counts.
Q: Can the same person have both capital gains and business income?
A: Yes. Investments produce capital gains (ITR-2 heads) and trading produces business income (ITR-3), each under its own rules.
Q: Are foreign shares capital gains or business income?
A: Foreign shares held as investments are capital gains; actively trading derivatives is business income – they’re different activities.
Q: What is non-speculative business income?
A: The category currency and other exchange-traded derivatives fall into – slab-taxed, with broad loss set-off and 8-year carry-forward.
Q: Does the new Income-tax Act 2025 change this?
A: The core classification (business income at slab rates) is retained; changes are mainly structural. It applies from FY 2026-27.
Q: Where can I see the exact tax computation?
A: See our full forex income-tax and ITR-filing guides for rates, audit and filing steps, and consult a chartered accountant.