
Key points on USD INR after fed
- The rupee ended October near 94.9 per dollar, about 1.2% stronger on the month, after nearing 97 early in October.
- The Fed’s 10–2 hold and a softer dollar after the meeting gave the rupee some relief, but high crude and FPI outflows limited gains.
- Analysts see a near-term range of about 94.50–95.50.
- November’s key events: the US midterms (results on 4 November in Indian hours), US jobs and CPI data, and the run-up to the RBI (4 December) and Fed (9 December).
What happened after the Fed
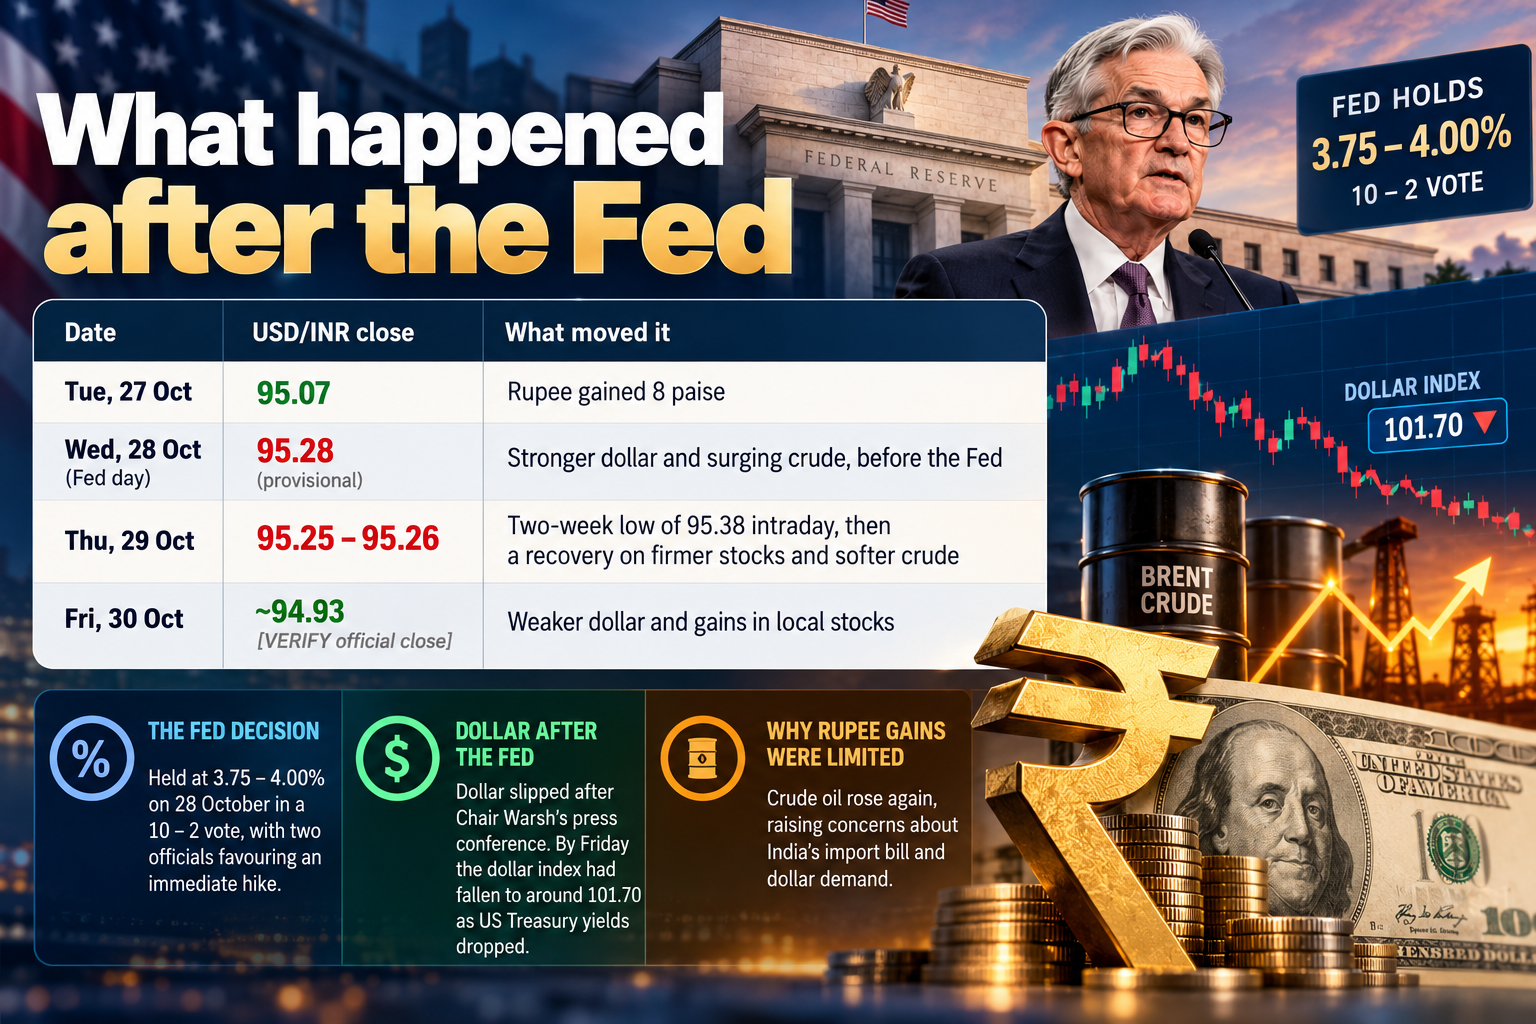
| Date | USD/INR close | What moved it |
|---|---|---|
| Tue, 27 Oct | 95.07 | Rupee gained 8 paise |
| Wed, 28 Oct (Fed day) | 95.28 (provisional) | Stronger dollar and surging crude, before the Fed |
| Thu, 29 Oct | 95.25–95.26 | Two-week low of 95.38 intraday, then a recovery on firmer stocks and softer crude |
| Fri, 30 Oct | ~94.93 | Weaker dollar and gains in local stocks |
The Fed held at 3.75–4.00% on 28 October in a 10–2 vote, with two officials favouring an immediate hike. The dollar slipped after Chair Warsh’s press conference. By Friday the dollar index had fallen to around 101.70 as US Treasury yields dropped. Worries about returns on heavy AI investment pushed money into bonds.
The rupee’s gains stayed limited because crude oil rose again, raising concerns about India’s import bill and dollar demand.
What drives the rupee in November
- The Fed and the dollar. Markets price about a 78% chance of a Fed hike on 9 December. Strong US data, with Q3 GDP at 3.4% and core PCE at 3.1%, supports that view. If US jobs and CPI data in November stay hot, the dollar could firm again, pressuring the rupee. Softer data would ease that pressure.
- Crude oil. Brent settled at $116.72 on 23 October, its highest since April. India imports most of its oil, so high prices raise dollar demand. Any de-escalation in the Middle East could bring quick relief, while new supply disruptions would hurt.
- FPI flows. Foreign investors withdrew roughly ₹48,000–52,000 crore from Indian equities in October, depending on the data source, after ₹35,861 crore in September. 2026 outflows now exceed ₹3 lakh crore. Domestic institutions have absorbed much of the selling, but the outflows still add to dollar demand.
- RBI action. The RBI has said it will keep currency moves orderly. In October it introduced a dollar window for oil companies and curbs on speculation in rupee derivatives. India’s reserves fell for six straight weeks, to $721.0 billion in the week to 16 October, consistent with intervention.
- The rate gap. The RBI raised its repo rate to 5.50% in October and signaled that cuts are off the table. If the Fed hikes in December while the RBI pauses, the rate gap could narrow, which may weigh on the rupee.
USD/INR levels to watch
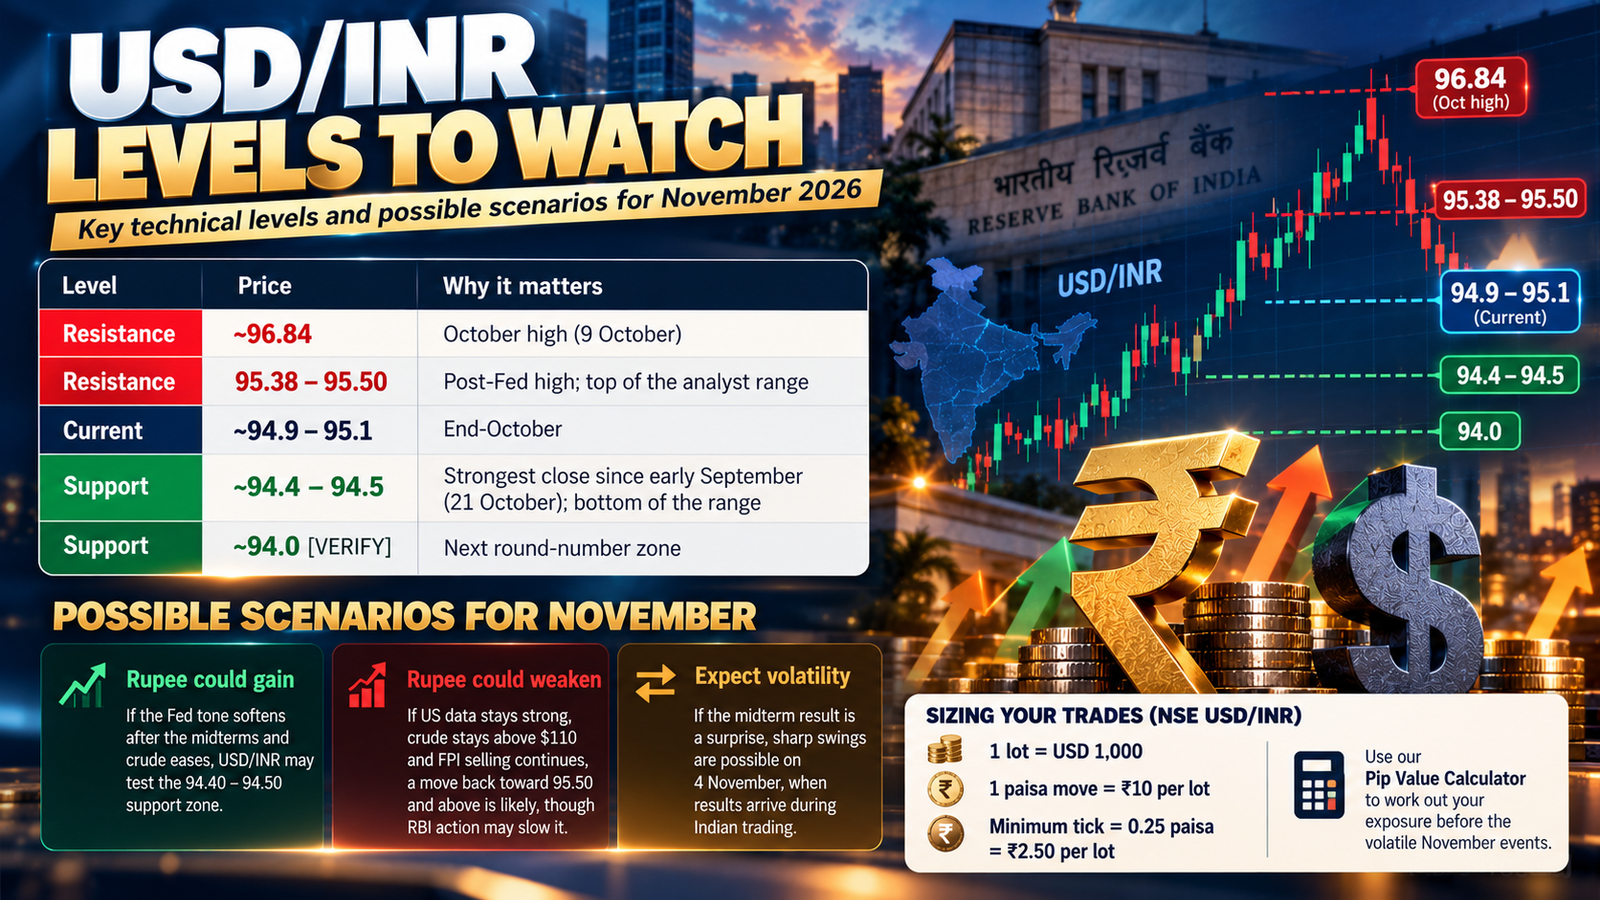
| Level | Price | Why it matters |
|---|---|---|
| Resistance | ~96.84 | October high (9 October) |
| Resistance | 95.38–95.50 | Post-Fed high; top of the analyst range |
| Current | ~94.9–95.1 | End-October |
| Support | ~94.4–94.5 | Strongest close since early September (21 October); bottom of the range |
| Support | ~94.0 | Next round-number zone |
Possible scenarios for November:
- If the Fed tone softens after the midterms and crude eases, USD/INR may test the 94.40–94.50 support zone.
- If US data stays strong, crude stays above $110 and FPI selling continues, a move back toward 95.50 and above is likely, though RBI action may slow it.
- If the midterm result is a surprise, sharp swings are possible on 4 November, when results arrive during Indian trading.
Sizing your trades: On NSE, one USD/INR lot is USD 1,000. A 1-paisa move is worth ₹10 per lot, and the minimum tick of 0.25 paise is worth ₹2.50. Use our Pip Value Calculator to work out your exposure before the volatile November events.
Impact on Indian traders
Timing matters this month: The US midterm results arrive during Indian trading hours on Wednesday, 4 November, when NSE currency trading opens at 09:00 IST. Most other major US data releases come after the NSE currency segment closes at 17:00 IST, so their effect shows the next morning.
INR crosses: GBP/INR could react to the BoE decision on 5 November, where a hike is expected. EUR/INR depends on French bond stress and the ECB’s December signal. JPY/INR depends on the BoJ’s path toward a December hike.
Currency pairs on NSE: NSE lists USD/INR, EUR/INR, GBP/INR and JPY/INR, plus EUR/USD, GBP/USD and USD/JPY. Trading forex with unauthorised offshore platforms is not permitted under FEMA.
November’s events could swing global risk appetite sharply. Our Risk-On / Risk-Off Meter can help you track it.
November calendar for rupee traders
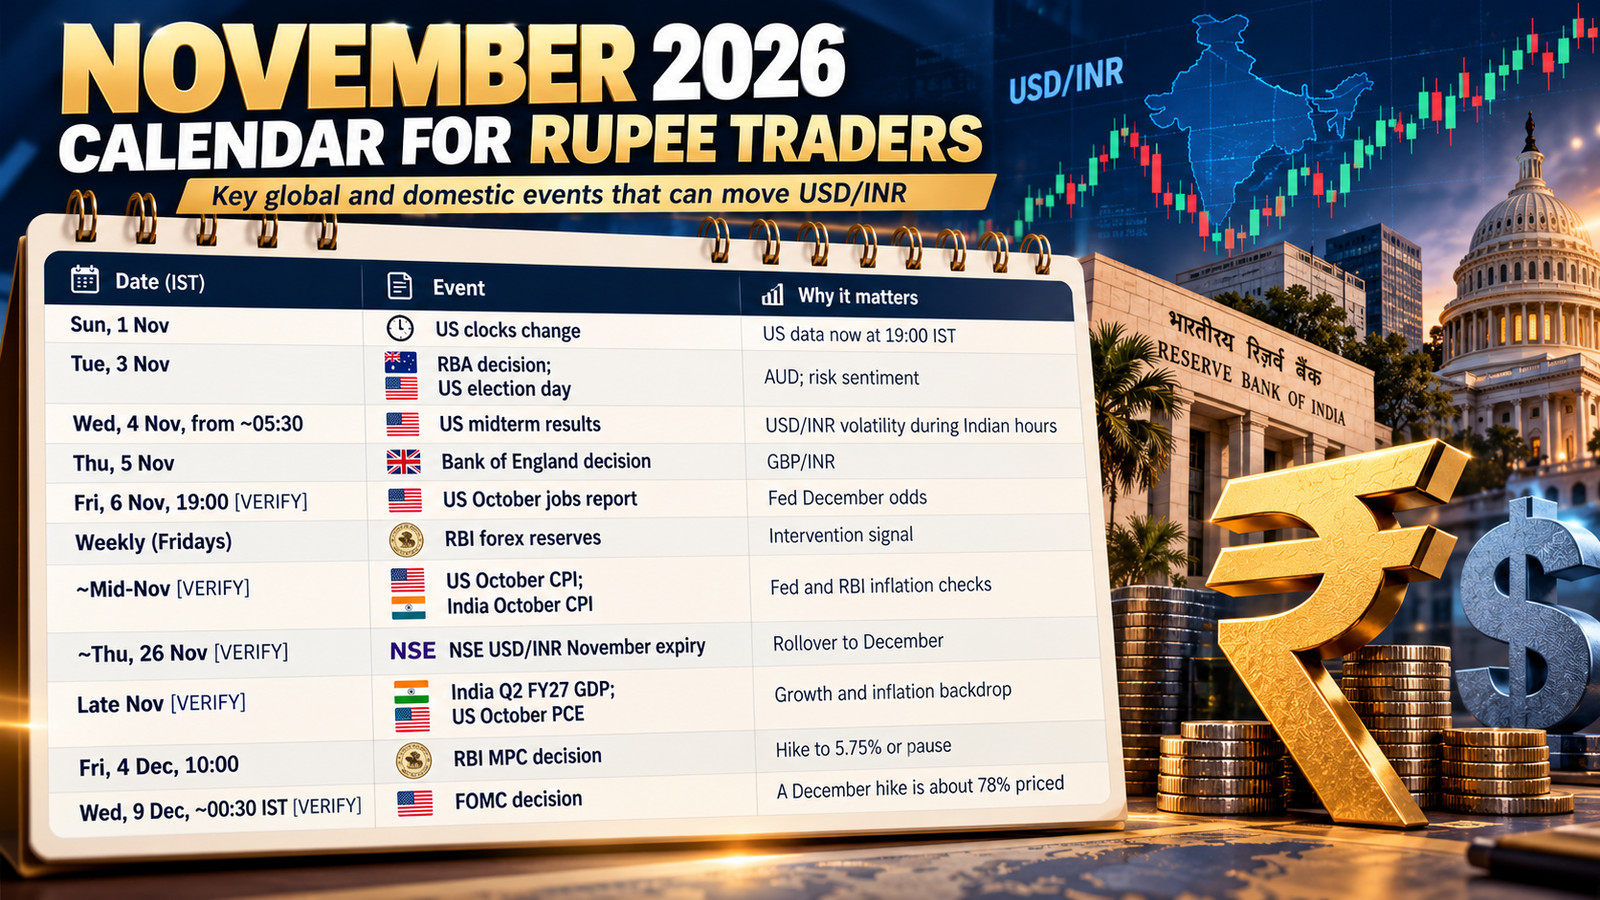
| Date (IST) | Event | Why it matters |
|---|---|---|
| Sun, 1 Nov | US clocks change | US data now at 19:00 IST |
| Tue, 3 Nov | RBA decision; US election day | AUD; risk sentiment |
| Wed, 4 Nov, from ~05:30 | US midterm results | USD/INR volatility during Indian hours |
| Thu, 5 Nov | Bank of England decision | GBP/INR |
| Fri, 6 Nov, 19:00 | US October jobs report | Fed December odds |
| Weekly (Fridays) | RBI forex reserves | Intervention signal |
| ~Mid-Nov | US October CPI; India October CPI | Fed and RBI inflation checks |
| ~Thu, 26 Nov | NSE USD/INR November expiry | Rollover to December |
| Late Nov | India Q2 FY27 GDP; US October PCE | Growth and inflation backdrop |
| Fri, 4 Dec, 10:00 | RBI MPC decision | Hike to 5.75% or pause |
| Wed, 9 Dec, ~00:30 IST | FOMC decision | A December hike is about 78% priced |
Track all release times on our Economic Calendar, and find more coverage in Market Analysis & News. Related: Fed rate decision October 2026, FII flows in October, India forex reserves update
FAQs
Where did USD/INR end October 2026?
Near 94.9 per dollar, about 1.2% stronger for the rupee over the month, after it neared 97 in early October.
How did the Fed decision affect the rupee?
The rupee touched a two-week low of 95.38 the day after the Fed’s hawkish 10–2 hold, then recovered as the dollar weakened and crude eased.
What will drive USD/INR in November 2026?
Mainly the Fed’s December outlook, crude oil prices, FPI flows, RBI intervention and the US midterm results on 4 November.