
Key points on central bank week forex
- Five major central banks decide in three days: the RBNZ, BoC and Fed on 28 October, the ECB on 29 October and the BoJ on 30 October.
- The Fed is widely expected to hold at 3.75–4.00%, with a December hike still heavily priced.
- The Bank of Canada is a close call between a hold at 2.25% and a hike. The ECB and BoJ are expected to hold.
- For Indian traders, the Fed decision late on 28 October IST is the key event for USD/INR.
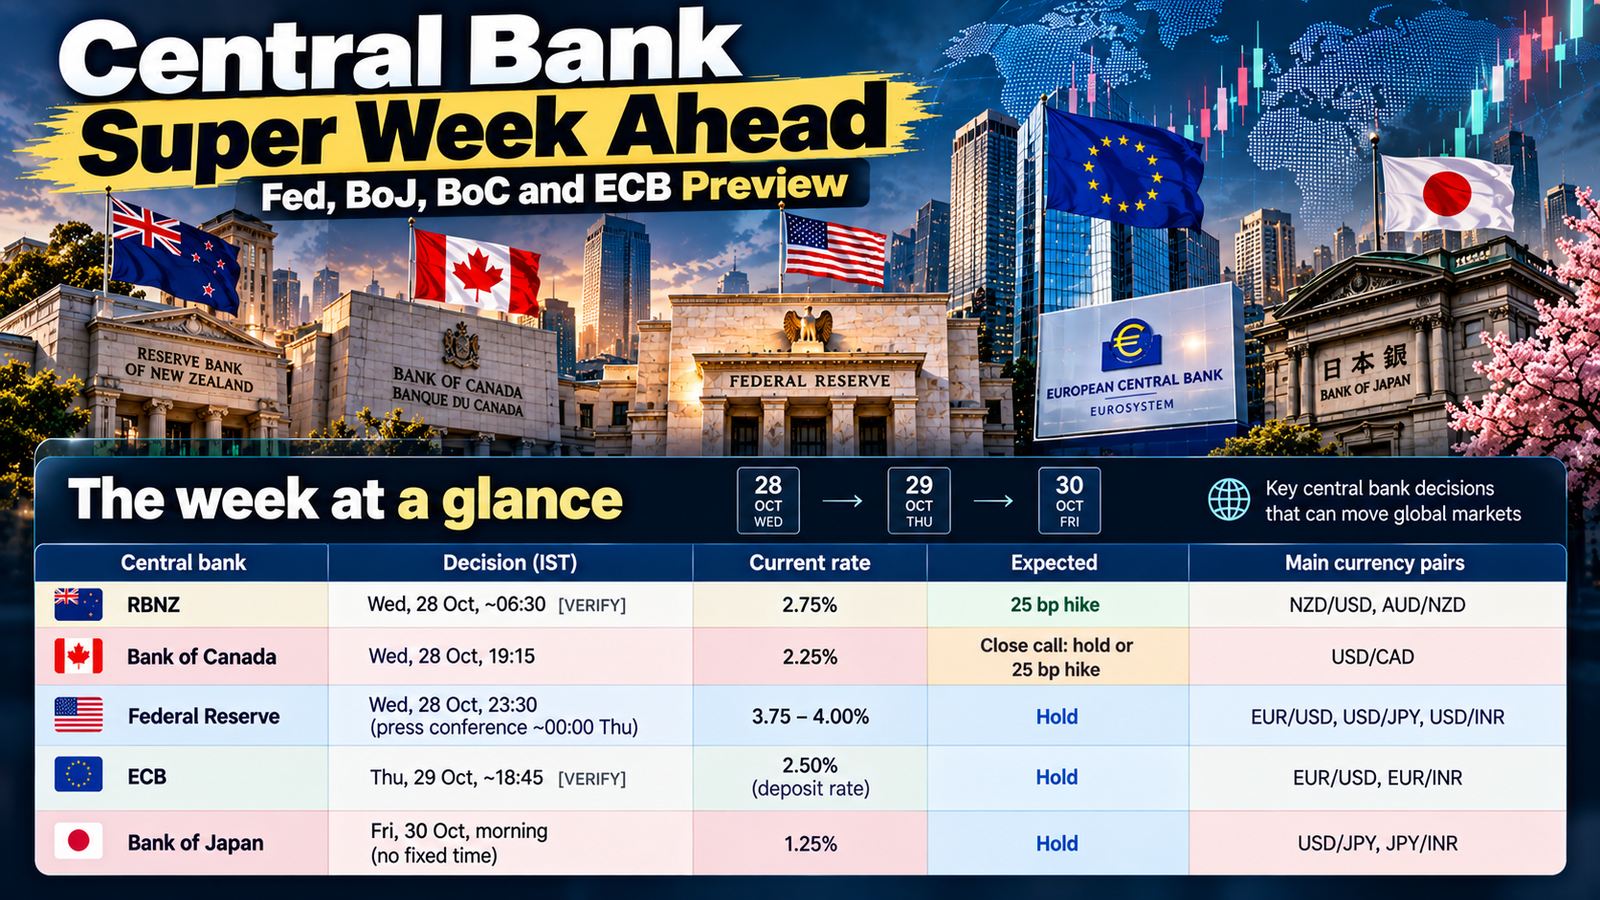
| Central bank | Decision (IST) | Current rate | Expected | Main currency pairs |
|---|---|---|---|---|
| RBNZ | Wed, 28 Oct, ~06:30 | 2.75% | 25 bp hike | NZD/USD, AUD/NZD |
| Bank of Canada | Wed, 28 Oct, 19:15 | 2.25% | Close call: hold or 25 bp hike | USD/CAD |
| Federal Reserve | Wed, 28 Oct, 23:30 (press conference ~00:00 Thu) | 3.75–4.00% | Hold | EUR/USD, USD/JPY, USD/INR |
| ECB | Thu, 29 Oct, ~18:45 | 2.50% (deposit rate) | Hold | EUR/USD, EUR/INR |
| Bank of Japan | Fri, 30 Oct, morning (no fixed time) | 1.25% | Hold | USD/JPY, JPY/INR |
The week at a glanceFederal Reserve: a hold, with December in focus
The Fed is expected to keep rates at 3.75–4.00% on 28 October. As of 20 October, CME FedWatch put the odds of a pause at about 83%, with about a 17% chance of a quarter-point hike. The same data showed about a 94% chance of at least one more hike by the December meeting.
What to watch: Chair Kevin Warsh has moved away from forward guidance. He has said he doesn’t prejudge meetings, and he described the October and December meetings as the points where the Fed takes stock of output, jobs and inflation. Without guidance, the statement wording and the press conference tone will carry more weight. US inflation is running at 3.7%, and high oil prices add to the case for further tightening.
Possible scenarios: If the Fed holds but signals that December is live, the dollar could steady after two weeks of losses. A surprise hike would likely lift the dollar sharply. A softer tone could extend the dollar’s slide.
Bank of Canada: the closest call of the week
The BoC has held its rate at 2.25% for almost a year. Its 28 October decision comes with a new Monetary Policy Report. Views are split. FXStreet’s week-ahead calendar lists a 25 bp hike. Prediction markets recently priced about a two-thirds chance of a hold. Some economists expect the BoC to wait until early 2027.
The case for a hike: Persistently high energy prices linked to the Iran conflict, and BoC surveys showing rising inflation expectations, with businesses planning to pass on higher costs.
The case for a hold: Signs of spare capacity in the economy, softer labour demand and uncertainty from US–Canada tariffs. September headline inflation was reported at 3.1%, but core inflation was lower.
ECB: a hold expected as French bond stress weighs
The ECB raised its deposit rate to 2.50% in September. It is expected to hold on 29 October, with markets eyeing a possible hike in December. This meeting has no new staff projections.
What to watch: France’s 10-year bond yield has climbed above 5%, reviving fears about the country’s debt. Newsquawk notes that the French fiscal and political situation has pushed up yields in a core eurozone member, which may reduce the room for further tightening. Last week’s eurozone flash PMI also missed forecasts. Watch President Lagarde’s comments on French spreads and on December.
Bank of Japan: a hold, with December in play
The BoJ is widely expected to keep its rate at 1.25% on 30 October and publish its Quarterly Outlook Report. Japan’s inflation rose above the 2% target in September, keeping a December hike in focus. Watch whether the BoJ’s language on inflation shifts from “approaching” the target to “having reached” it. See our detailed USD/JPY Outlook Ahead of the BoJ
RBNZ and others
The RBNZ (2.75%) is expected to raise rates by 25 bp on 28 October, and the Bank of Thailand is expected to hold. Australia’s Q3 CPI on 28 October will also shape expectations for the RBA meeting on 3 November.
Why the order matters
The Fed goes first, so its decision sets the dollar backdrop for the BoC, ECB and BoJ that follow. Newsquawk notes that in weeks like this, markets trade less on individual decisions and more on the sequence. The dollar side of any surprise from the other banks depends on what the Fed has already done to rate differentials. Data adds to the mix: US Q3 GDP and September PCE inflation land on 29 October, on the same day as the ECB.
Impact on Indian traders
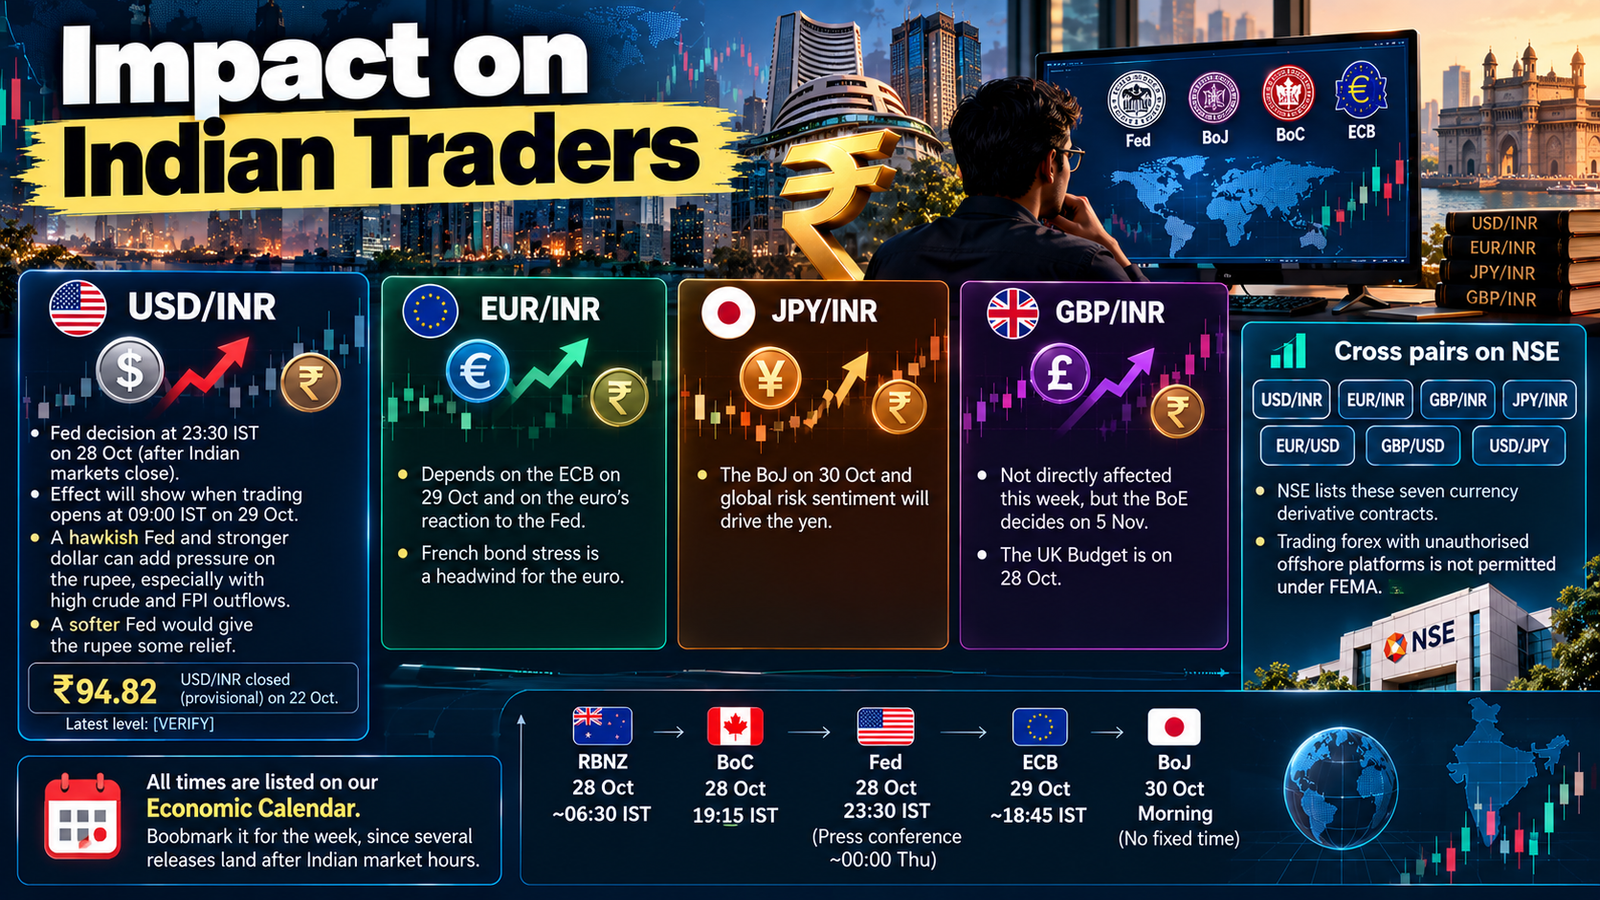
USD/INR: The Fed decision comes at about 23:30 IST on 28 October, after Indian currency markets close. Its effect will show when trading opens at 09:00 IST on 29 October. A hawkish Fed and a stronger dollar would add pressure on the rupee, on top of high crude and FPI outflows. A softer Fed would give the rupee some relief. USD/INR closed at 94.82 (provisional) on 22 October.
EUR/INR: Depends on the ECB on 29 October and on the euro’s reaction to the Fed. French bond stress is a headwind for the euro.
JPY/INR: The BoJ on 30 October and global risk sentiment will drive the yen.
GBP/INR: Not directly affected this week, but the BoE decides on 5 November, and the UK Budget is on 28 October.
Cross pairs on NSE: NSE lists USD/INR, EUR/INR, GBP/INR and JPY/INR, plus EUR/USD, GBP/USD and USD/JPY. Trading forex with unauthorised offshore platforms is not permitted under FEMA.
All times are listed on our Economic Calendar. Bookmark it for the week, since several releases land after Indian market hours.
What else to watch this week
| Date (IST) | Event |
|---|---|
| Tue, 27 Oct | US consumer confidence; ECB bank lending survey |
| Wed, 28 Oct | Australia Q3 CPI; UK Autumn Budget; Jio Platforms listing |
| Thu, 29 Oct, ~18:00 | US Q3 GDP and September PCE |
| Fri, 30 Oct | Tokyo CPI; Eurozone Q3 GDP; Germany CPI; RBI forex reserves (evening) |
| Sun, 1 Nov | US clocks change; US times move one hour later in IST |
| Tue, 3 Nov | US midterm elections; RBA decision |
FAQs
When is the Fed decision in IST?
The Fed announces its decision at 2:00 pm US Eastern time on Wednesday, 28 October, which is 23:30 IST. The press conference follows about 30 minutes later.
Which central banks are expected to change rates this week?
The RBNZ is expected to hike by 25 bp. The Bank of Canada is a close call. The Fed, ECB and BoJ are expected to hold.
How will this week affect USD/INR?
Mainly through the Fed. A hawkish message could strengthen the dollar and weigh on the rupee when Indian markets open on 29 October, while a softer tone may ease pressure.