Key points forex weekly wrap oct
- Of five major central banks, only the Bank of Canada hiked. The Fed, ECB and BoJ held but pointed to December, while the RBNZ surprised with a hold.
- An AI-led tech sell-off hit Wall Street, and the Nasdaq fell 2.86% on Friday. It drove money into bonds, pushing US yields and the dollar lower.
- Gold fell 3.6% on Friday to about $3,885, its lowest of 2026, despite falling yields.
- The rupee ended the week firmer at about 94.93, helped by the weaker dollar.
Central bank scorecard
| Central bank | Date | Decision | Signal |
|---|---|---|---|
| RBNZ | Wed, 28 Oct | Held at 2.75% (4–3 vote) | Surprise hold; hike was ~90% priced; tightening still likely |
| Bank of Canada | Wed, 28 Oct | Hiked 25 bp to 2.50% | First hike since 2023; more may be needed |
| Federal Reserve | Wed, 28 Oct | Held at 3.75–4.00% (10–2) | Two dissents for a hike; December live |
| ECB | Thu, 29 Oct | Held at 2.50% | Hike debated; December likely; Lagarde to leave in February 2027 |
| Bank of Japan | Fri, 30 Oct | Held at 1.25% (8–1) | Declared underlying inflation at 2%; December hike in play |
What happened this week
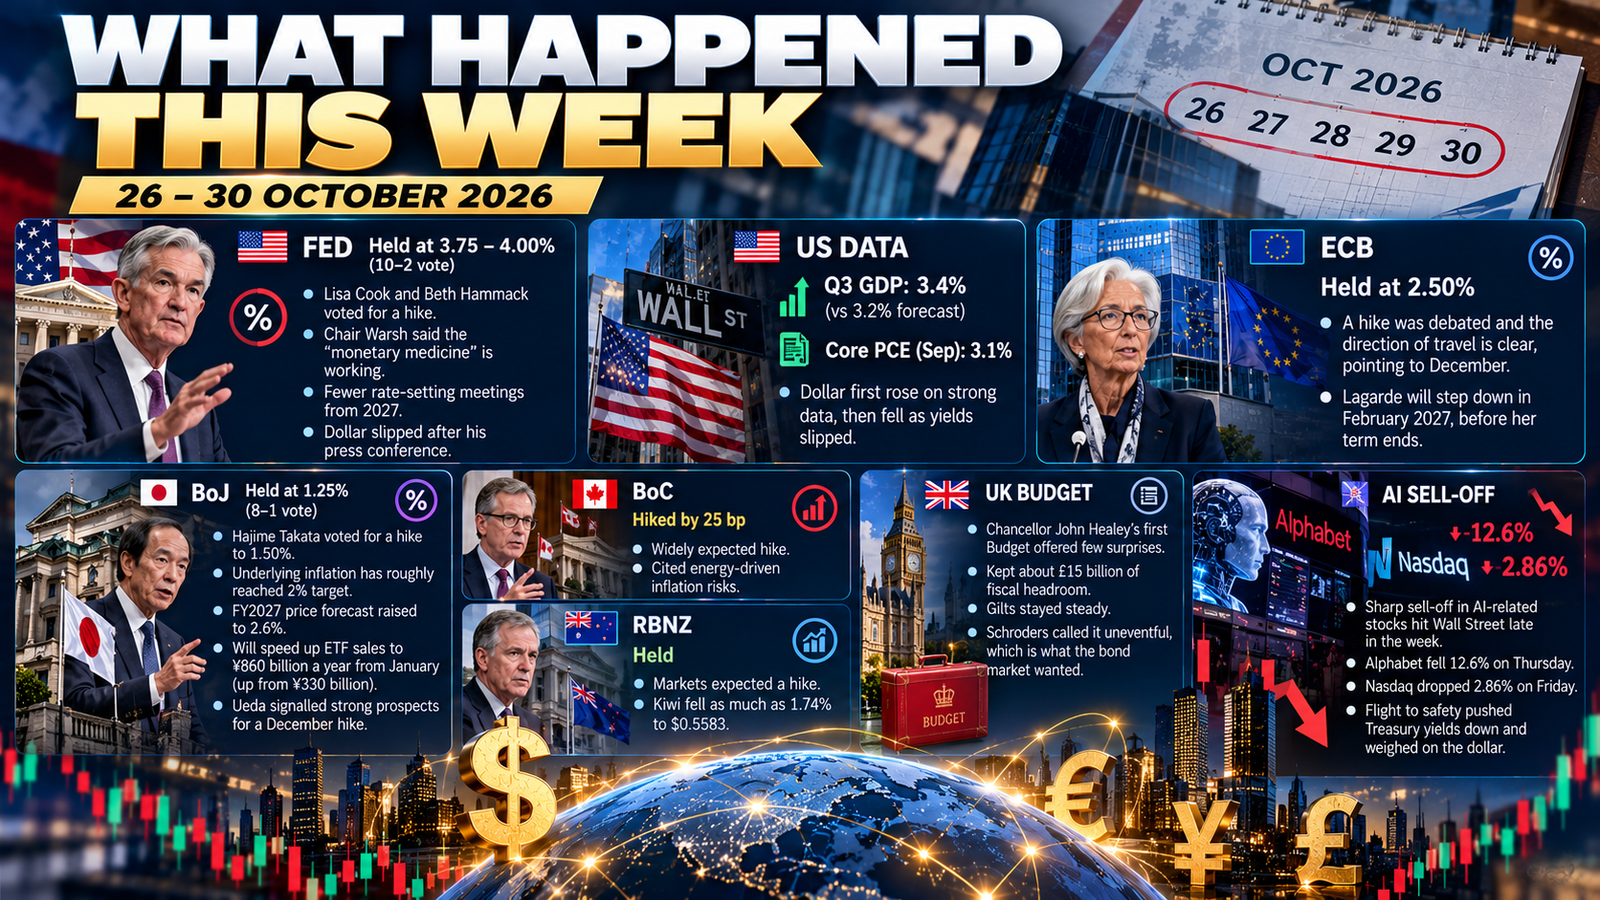
Fed: The Fed held rates in a 10–2 vote, with Lisa Cook and Beth Hammack wanting a hike. Chair Warsh said the “monetary medicine” is working and announced fewer rate-setting meetings from 2027. The dollar slipped after his press conference.
US data: Q3 GDP grew 3.4%, above the 3.2% forecast, and September core PCE rose to 3.1%. The dollar first rose on the data, then fell as yields slipped.
ECB: The ECB held at 2.50%. Lagarde said a hike was debated and the direction of travel is clear, which points to December. Separately, she announced she will step down in February 2027, before her term ends.
BoJ: The BoJ held at 1.25% in an 8–1 vote, with Hajime Takata voting for a hike to 1.50%. The bank said underlying inflation has roughly reached its 2% target and raised its FY2027 price forecast to 2.6%. It will also speed up sales of its ETF holdings to ¥860 billion a year from January, up from ¥330 billion. Ueda signalled strong prospects for a December hike but gave few fresh clues on timing.
Bank of Canada and RBNZ: The BoC delivered a widely expected 25 bp hike, citing energy-driven inflation risks. The RBNZ held when markets expected a hike, and the kiwi fell as much as 1.74% to $0.5583.
UK Budget: Chancellor John Healey’s first Budget offered few surprises. It kept about £15 billion of fiscal headroom, and gilts stayed steady. Schroders called it uneventful, which is what the bond market wanted.
AI sell-off: A sharp sell-off in AI-related stocks hit Wall Street late in the week. Alphabet fell 12.6% on Thursday, and the Nasdaq dropped 2.86% on Friday. The flight to safety pushed Treasury yields down and weighed on the dollar.
Weekly scorecard
| Market | Late-week level | Week | What moved it |
|---|---|---|---|
| DXY | ~101.70 (Fri) | Down | Lower Treasury yields after the AI sell-off; Fed seen as slightly less hawkish |
| EUR/USD | 17-month low of 1.1105 on Thu | Mixed | Strong US data, then a dollar sell-off; ECB caution; Lagarde’s exit |
| GBP/USD | above 1.3350 on Thu | – | Calm Budget; BoE hike expected on 5 Nov |
| USD/JPY | ~157.1–157.6 after the BoJ | Down | Hawkish BoJ hold; lower US yields |
| NZD/USD | Low of $0.5583 on Wed | Down | RBNZ surprise hold |
| USD/CAD | Six-week low near 1.3968 | Down | BoC hike; softer US dollar |
| Gold (XAU/USD) | ~$3,885 (Fri) | Down | Fell 3.6% Fri to a 2026 low; 27% below its January record |
| Brent crude | – | – | Middle East supply risks; US–Iran talk hopes |
| USD/INR | ~94.93 (Fri) | Rupee firmer | Weaker dollar; local stock gains |
Why it mattered
Central banks are diverging. Most major central banks still lean toward tightening because of energy-driven inflation. But the RBNZ’s surprise hold and the ECB’s caution over French bond stress show not all of them are moving at the same pace. December is now a key month for the Fed, ECB, BoJ and RBNZ.
The dollar lost its edge late in the week. Markets scaled back expectations for Fed hikes beyond December. The AI sell-off pushed money into Treasuries, lowering yields and the dollar.
Gold didn’t act as a safe haven. Gold fell even as yields dropped. Analysts pointed to position-cutting during the stock sell-off. Gold often falls in the early stages of a market crash as investors sell what they can to raise cash.
Impact on Indian traders
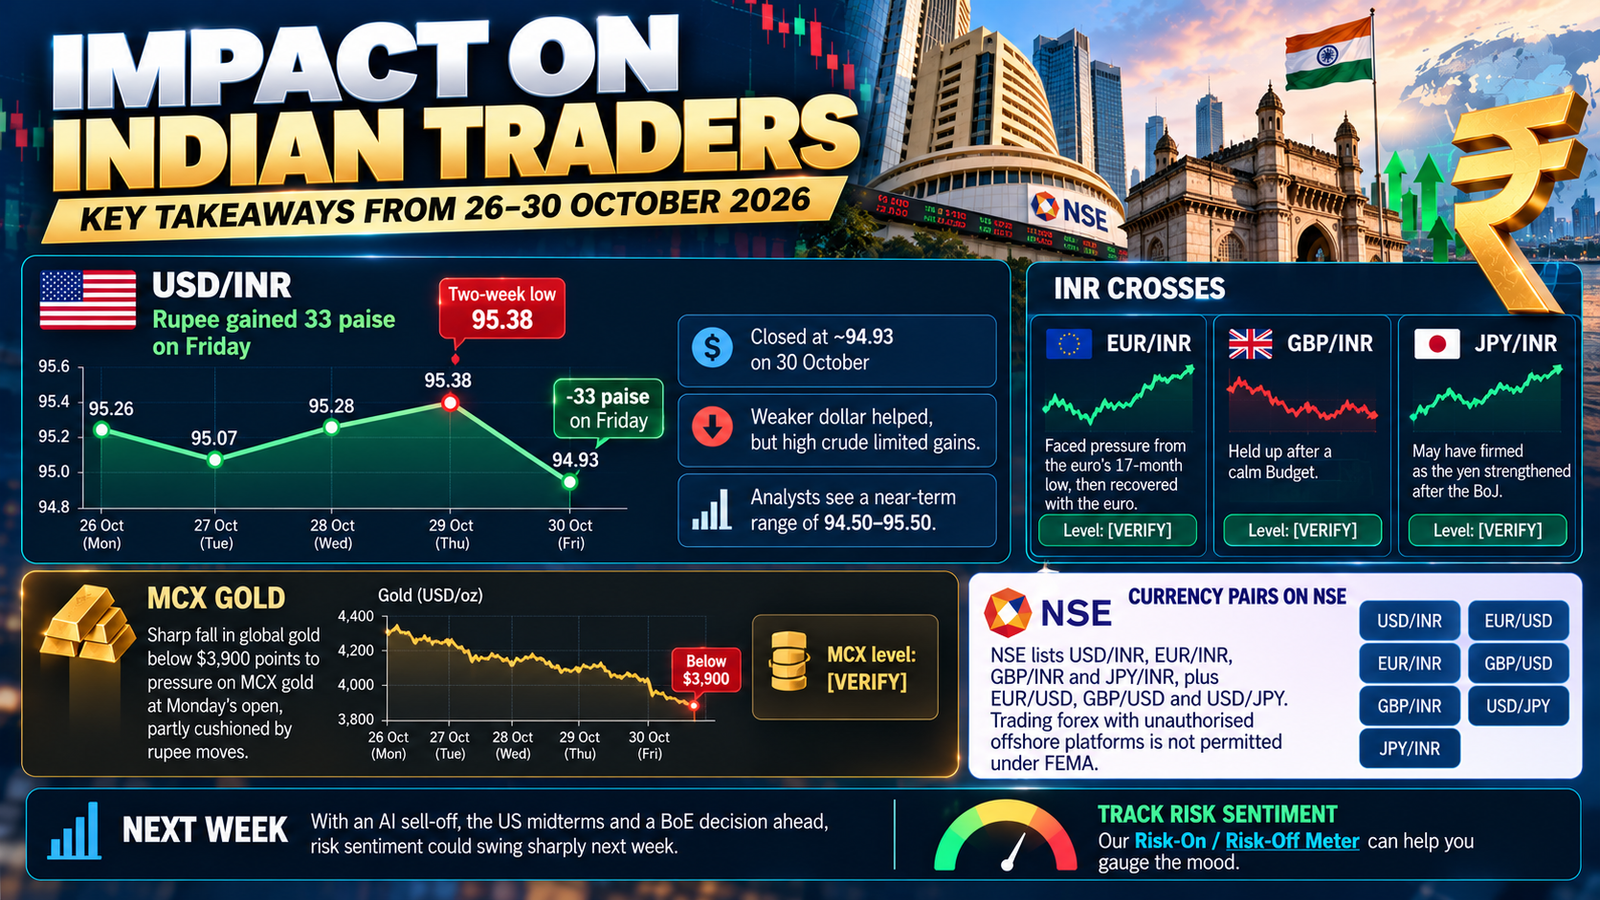
USD/INR: The rupee gained 33 paise on Friday to close at about 94.93, after touching a two-week low of 95.38 on Thursday after the Fed. The weaker dollar helped, but high crude limited gains. Analysts see a near-term range of 94.50–95.50.
INR crosses: JPY/INR may have firmed as the yen strengthened after the BoJ. EUR/INR faced pressure from the euro’s 17-month low, then recovered with the euro.
MCX gold: The sharp fall in global gold below $3,900 points to pressure on MCX gold at Monday’s open, partly cushioned by rupee moves.
Currency pairs on NSE: NSE lists USD/INR, EUR/INR, GBP/INR and JPY/INR, plus EUR/USD, GBP/USD and USD/JPY. Trading forex with unauthorised offshore platforms is not permitted under FEMA.
With an AI sell-off, the US midterms and a BoE decision ahead, risk sentiment could swing sharply next week. Our Risk-On / Risk-Off Meter can help you gauge the mood.
What to watch next week (2–6 November)
| Date (IST) | Event | Why it matters |
|---|---|---|
| Sun, 1 Nov | US clocks change | US data now at 19:00 IST |
| Mon, 2 Nov, ~20:30 | US ISM manufacturing PMI (forecast 54.7) | Growth check |
| Tue, 3 Nov | RBA decision; US election day | AUD; risk sentiment |
| Wed, 4 Nov, from ~05:30 | US midterm results | USD/INR volatility during Indian hours |
| Wed, 4 Nov, 15:30 | Eurozone October flash inflation | Key input for a December ECB hike |
| Thu, 5 Nov | Bank of England decision | A hike to 4.00% is expected |
| Fri, 6 Nov, 19:00 | US October jobs report | The main event for the dollar and gold |
| Fri, 6 Nov (evening) | RBI forex reserves | Intervention signal |
Possible scenarios:
- If the AI sell-off deepens, safe-haven flows may keep US yields and the dollar under pressure, while the yen could gain.
- If US jobs data is strong and the midterms pass smoothly, December Fed hike bets could firm and the dollar may recover.
- If the BoE hikes as expected and signals more, sterling and GBP/INR could firm.
Track all release times on our Economic Calendar, and find more coverage in Market Analysis & News. Related this week: Fed decision recap, ECB decision, BoJ decision, BoC decision, RBNZ decision, US GDP and PCE, Eurozone GDP and inflation, USD/INR November outlook
FAQs
Which central banks changed rates in the week of 26–30 October 2026?
Only the Bank of Canada, which hiked by 25 bp to 2.50%. The Fed, ECB, BoJ and RBNZ all held.
Why did gold fall below $3,900?
Gold fell 3.6% on Friday as an AI-led stock sell-off triggered broad selling. It has also been weighed down by expectations of further Fed hikes, even though Treasury yields fell late in the week.
How did the rupee perform this week?
The rupee touched a two-week low of 95.38 after the Fed, then strengthened to about 94.93 on Friday as the dollar weakened.